
Picture this: It’s a sunny Saturday morning in Florida. You’re sipping coffee in the kitchen, sunlight streaming in, retirement paperwork spread across the table. For years, you’ve heard the same advice—“just keep saving. ” Now, it’s time to decide how you’ll turn savings into security. Few choices are as final (or as important) as deciding between the FRS pension vs investment plan Florida options—especially since your whole financial future might hinge on getting this right. If you feel lost in the sea of forms, you’re not alone, and we’re going to navigate these waters together.
A Real-Life Crossroads: Choosing Between the FRS Pension and Investment Plan in Florida
Every week, I sit down with people just like you—current or retired Florida public employees, faculty and staff, sometimes even couples, each with the same big decision: Do I choose the guaranteed FRS pension, or do I steer my own ship with the investment plan? This decision affects your monthly income, your spouse’s financial security, and whether your money can weather the markets for the rest of your life. Unlike the sales pitches you might have suffered through before, I’m here to earn your trust by explaining, not selling. Let’s break down what these options truly mean—without the jargon, straight from my kitchen table to yours.
“Retirement isn’t just about stopping work — it’s about making sure the life you want keeps going, month after month, bill after bill. You deserve to know what your options really mean for your household, without jargon or a sales pitch.” – Ken Keplinger
What You’ll Learn About FRS Pension vs Investment Plan Florida
-
The core differences between the FRS pension and investment plan Florida options
-
How each plan handles retirement income, survivorship, and market risk
-
Tradeoffs between guaranteed income and investment flexibility
-
Real-world outcomes for Florida retirees
-
Questions to ask before you make an irrevocable choice
Understanding the Basics: FRS Pension vs Investment Plan Florida
What is the Florida Retirement System (FRS)?
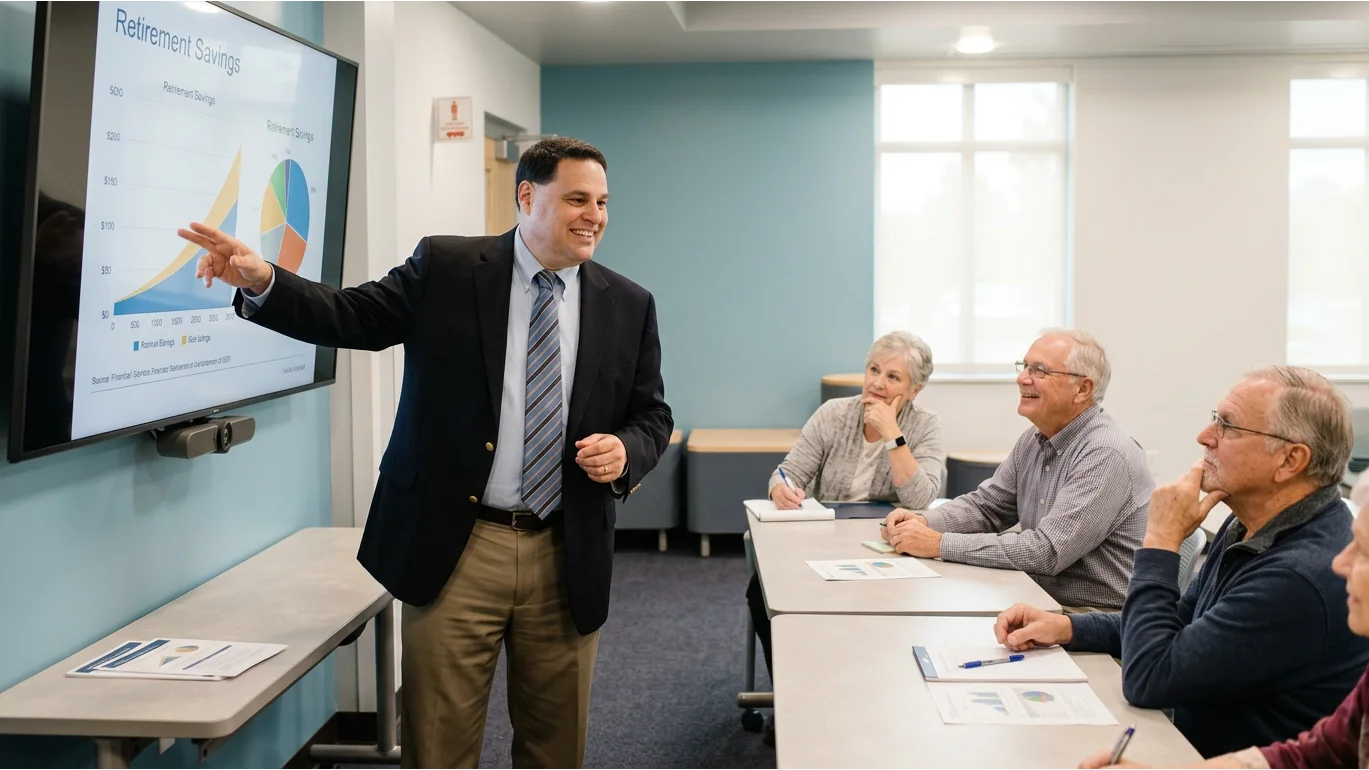
The Florida Retirement System (FRS) is the benefit program for Florida’s public sector employees—think teachers, county workers, university faculty and staff, and police officers. As a participant, you’re given a choice: stick with the FRS pension plan, which acts like a traditional monthly paycheck during retirement, or elect the investment plan, where your retirement savings grow in a personal account you manage (a bit like a 401(k)). Most current employees are nudged to choose within the first eight months of starting their public job, but plenty of folks are unsure or overwhelmed by the details. The real issue? This choice may be irrevocable after a switch.
The FRS is much more than a savings account. It’s an ecosystem, with programs including the health insurance subsidy, deferred compensation opportunities, and resources to enhance your overall earnings and protect your financial future. Many public employees never get the straight scoop about how these options impact retirement security, so my job is to give you information regarding your retirement options, including how you can access information and use the plan to enhance your overall earnings or provide for your spouse.
How the FRS Pension Plan Works
The FRS pension plan is a straightforward promise: for every year you work in a covered position, you earn a credit toward monthly income in retirement (called a “defined benefit”). When you retire, payments arrive like clockwork—regardless of what the stock market does that year. The formula takes into account your years of service and your highest average salary; it’s designed to provide steady, predictable income. This helps you cover monthly bills and major expenses, like vacations or healthcare, without wondering if your money will last. For many, this “guaranteed check” removes the financial stress of retirement entirely.
But, as with everything, there are tradeoffs. The pension plan generally offers less flexibility if you want to leave behind a lump sum for children or charities, or if you plan to move your career out of public service. Some specific programs, including the health insurance subsidy, are tightly linked to pension participation as well. My advice? See the numbers—black and white, no guesswork—before you decide.
How the FRS Investment Plan Works
The FRS investment plan is more flexible but comes with more personal responsibility. Instead of an automatic pension, your employer’s contributions (and yours) fund a personal investment account, where you select funds and track the balance—a model similar to popular 401(k) plans you might know. When you retire or leave public service, you can manage withdrawals (within the rules), work with an advisor, and potentially leave the remainder to beneficiaries.
While the investment plan offers control and the possibility for growth, it also shifts market risk and longevity risk onto your shoulders. The plan’s value depends on what the markets do and how soon you withdraw. The retirement industry is full of document readers, download links, charts, and jargon. My job is to help you access information, understand compensation opportunities, and see clearly what those account numbers might mean for your retirement lifestyle.
Explaining the Basics: FRS pension vs investment plan Florida Visual Overview
Comparing FRS Pension vs Investment Plan Florida on Key Factors
Guaranteed Income vs. Flexibility
It all boils down to what matters most to you—safety, predictability, or flexibility and control. The pension plan is like owning a steady lighthouse; come rain or shine, your monthly paycheck appears on time, helping you handle bills, plan vacations, and sleep at night. This matters a lot to someone who is tired of market swings and just wants a stable anchor.
On the flip side, the investment plan allows you to plan for your own adventures. You manage your investments, withdraw when you wish (inside the plan rules), and can potentially leave remaining funds to your heirs. But you alone absorb the ups and downs—the peaks mean opportunities, but the valleys can be harsh, especially in a shaky market or if you have health considerations. Both plans include insurance subsidy benefits and programs including health insurance, but such details are best weighed alongside your priorities, desired lifestyle, and overall earnings goals.
Market Risk and Upside Potential
The investment plan is tied to the markets. If you enjoy following the ups and downs, and want the potential for higher returns, managing these investments can be rewarding. But this also means your nest egg can go down as well as up. If the market dips right after you retire, or if you live longer than average, you might worry about running out of money.
Conversely, the pension plan shields you from market volatility. Your monthly check remains the same regardless of a recession or boom time, giving you peace of mind. That said, your payments usually won’t grow much with inflation (unless you choose certain options), so if prices rise rapidly over time, the real value of those monthly checks could shrink. It’s a tradeoff: growth potential with risk, or stability with less flexibility for your estate.
Spousal and Survivor Benefits

For many, family comes first. The FRS pension plan offers robust spousal and survivor benefit choices—monthly income that can continue to your spouse, ensuring they’re not left in a bind if you pass away first. This “joint and survivor” option is popular among married retirees or those supporting a dependent child. The tradeoff? Choosing survivor protection can reduce your monthly benefit a bit, but it may be worth every penny for that sense of security.
The investment plan gives you flexibility. Whatever is left in your account at death goes directly to your named beneficiaries, usually without probate delay. If leaving a lump sum—perhaps to children, charities, or even a trust—is a top priority, this option deserves a look. Just know, the balance can rise—or fall—based on the market, and it’s up to you to plan distributions so your loved ones are provided for long after you’re gone.
What Happens If You Leave Public Service?
You’re not alone if you’re eyeing a second act—maybe a later-in-life career or a move to another state. If you leave public service before reaching retirement eligibility, the investment plan offers easier portability: you can take your vested balance and roll it into an IRA or another qualified plan. This makes it appealing if you anticipate changing jobs or careers.
The pension plan gets trickier. If you leave early, your pension benefit is frozen and won’t start until you reach retirement age. Sometimes, the math works out fine; other times, penalties or lower benefits might surprise you. Access information regarding your retirement options and consider your overall earnings trajectory before making a permanent choice.
|
FRS Pension vs Investment Plan Florida: Feature-by-Feature Comparison |
||
|
Feature |
Pension Plan |
Investment Plan |
|---|---|---|
|
Monthly Income Security |
Lifetime, guaranteed, based on service and salary |
Market-based; varies with withdrawals and investment performance |
|
Flexibility / Control |
Limited; little control after retirement |
High; you set withdrawal schedule and manage investments |
|
Spousal & Survivor Options |
Joint and survivor annuity choices |
Account paid to named beneficiaries; lump sum possible |
|
Market Risk |
None for retiree; risk borne by the state |
Entirely on the individual |
|
Leaving Employment Early |
Frozen benefit, may require waiting until retirement age |
Portable; can roll account to IRA or new employer’s plan |
|
Cost of Living Adjustment (COLA) |
Limited or none (for most members) |
Depends on investment returns and withdrawal rate |
Making the Decision: Which FRS Option is Right for Your Financial Future?
Personal Factors: Family, Age, Health, and Peace of Mind
No two lives look alike, and no two retirements should either. In my kitchen, I always start with your priorities. Are you hoping never to worry about a bill, even if you live to 100? Are you healthier than average, or dealing with an illness in the family? Do you sleep better knowing your spouse has a safety net, or do you want flexibility to move, switch jobs, or leave a legacy for your grandchildren or favorite charity? Your decisions on retirement options, health insurance, deferred compensation, and programs including insurance subsidy must fit your real hopes—not just the numbers.
My own journey through these crossroads wasn’t easy, even after decades of helping others steer. If you’re weighing these plans, I’ll walk with you through every what-if, run the numbers you actually care about, and show you the impact of each choice on your life. That approach isn’t a sales pitch; it’s how I’d want to be treated in your shoes.
Questions I Ask Every Client Deciding Between FRS Pension and Investment Plan
-
Who relies on your income now—and who would need it after you’re gone?
-
How comfortable are you managing investments or weathering market swings?
-
If you or your spouse face chronic illness, does that change your priorities?
-
Do you want to leave a specific sum to heirs, or is “monthly bills covered” the goal?
-
How do you feel about not being able to switch back after committing?
“No two retirements are alike. What gives one person peace of mind could keep another up at night. My job is to light your way, not steer your ship.” – Ken Keplinger
How I Walk Clients Through the FRS Choice Process (Client Story Example)
People Also Ask: FRS Pension vs Investment Plan Florida Common Questions
Which is better, a Pension Plan or an Investment Plan?
Both the FRS pension and investment plan Florida have strengths, depending on your personal goals. If you want predictable monthly income that lasts as long as you do—and protection for your spouse—the pension plan offers long-term certainty. If you prefer to actively manage your money and are comfortable with market ups and downs, the investment plan offers flexibility and the chance for growth. The best choice depends on your situation.
Can I switch from Investment Plan to Pension Plan in FRS?
Yes, but with careful rules. FRS allows one opportunity to switch—and once done, it’s generally irrevocable. The value of your investment account is transferred to fund your pension benefit. Knowing the timing and impact is critical before making this choice.
Is FRS pension worth it?
For many, the FRS pension is worth it for the lifetime income and reduced worry about market downturns in retirement. But it may offer less flexibility, especially around leaving a lump sum for heirs. Each person’s priorities matter—this is why we run the numbers together in black and white.
What age can you retire from an FRS investment plan?
For most members, you can retire and start drawing from the FRS investment plan at age 59½ without penalty. Earlier withdrawal may trigger taxes and penalties—and, crucially, you need a withdrawal strategy so your money lasts as long as you do.
Key Takeaways: FRS Pension vs Investment Plan Florida
-
The FRS pension plan offers steady, lifetime income; the investment plan offers choices and flexibility.
-
Your personal priorities—such as worry, family protection, and control—matter as much as the math.
-
Once you switch, you often can’t go back. Get advice in black and white you can understand.
-
I’m here to light the way, not push a product. Your peace of mind comes first.
Frequently Asked Questions about FRS Pension vs Investment Plan Florida
-
What is the default if I don’t choose?
If you don’t actively choose, FRS will default you into the pension plan after your eight-month window—unless otherwise specified by your employer. Whichever plan you end up with shapes your retirement options for years to come, so don’t leave this to chance. -
How does health affect which plan is better?
Health is a huge factor. If you’re facing medical challenges or have a shorter than average life expectancy, the investment plan’s lump-sum options or flexible withdrawals might be more attractive. But for those planning a long retirement, the pension’s regular monthly check can offer peace of mind. -
Can I leave these benefits to my spouse or children?
Yes—each plan handles this differently. The pension offers survivor options for a spouse but less for other heirs. The investment plan pays any remaining funds to your named beneficiaries. Be sure to review your beneficiary forms regularly. -
Do these plans offer any cost of living adjustment?
The pension plan’s cost of living adjustment (COLA) is extremely limited for most current employees. The investment plan does not offer automatic increases, so your only “adjustment” is the performance of your investments. -
What happens if I move out of Florida?
Both plans can pay you no matter where you live in retirement. The key differences—market risk, flexibility, survivorship—apply equally in or out of state.
Ready to See Your Income Plan in Writing?
Let’s put your income plan in writing: https://safemoneysteps.com/
Conclusion: When it comes to your financial future, peace of mind should lead the way. If you’re ready to decide, or need to see every scenario in black and white, I’m here to light your path—no pressure, ever.
